
Decide to rent or buy lab metrology gear with 60–70% utilization thresholds, a TCO checklist, financing options, and a hybrid fleet approach.

Renting suits low or unpredictable utilisation, short projects and validation work; buying or leasing suits high, stable daily use and audit critical processes. The tiebreaker is usually utilisation: instruments used under roughly 30 to 35 weeks a year rarely justify ownership once you count calibration downtime. Many operations end up running a hybrid fleet, and PCS Precision supports either path.
TL;DR:
- Renting is most cost-effective for instruments used less than 60 to 70 percent of the time, roughly under 30 to 35 weeks annually, due to fixed ownership costs.
- Ownership is advantageous when an instrument is used continuously for critical processes that require long-term stability, calibration, and audit traceability.
- Hybrid fleets combining owned core equipment with rented specialty or seasonal items typically reduce total costs by 25 to 40 percent.
- Calibration, servicing, and downtime costs significantly influence the total cost of ownership and must be factored into the decision.
- Selecting the appropriate option depends on utilization, revenue impact, funding structure, calibration capabilities, and compliance requirements.
Renting wins whenever the need is temporary, uncertain, or tied to a deadline you don’t control. A validation campaign, a six month supply contract, or a grant that hasn’t landed yet are all situations where locking capital into a force gauge or data logger makes little sense.
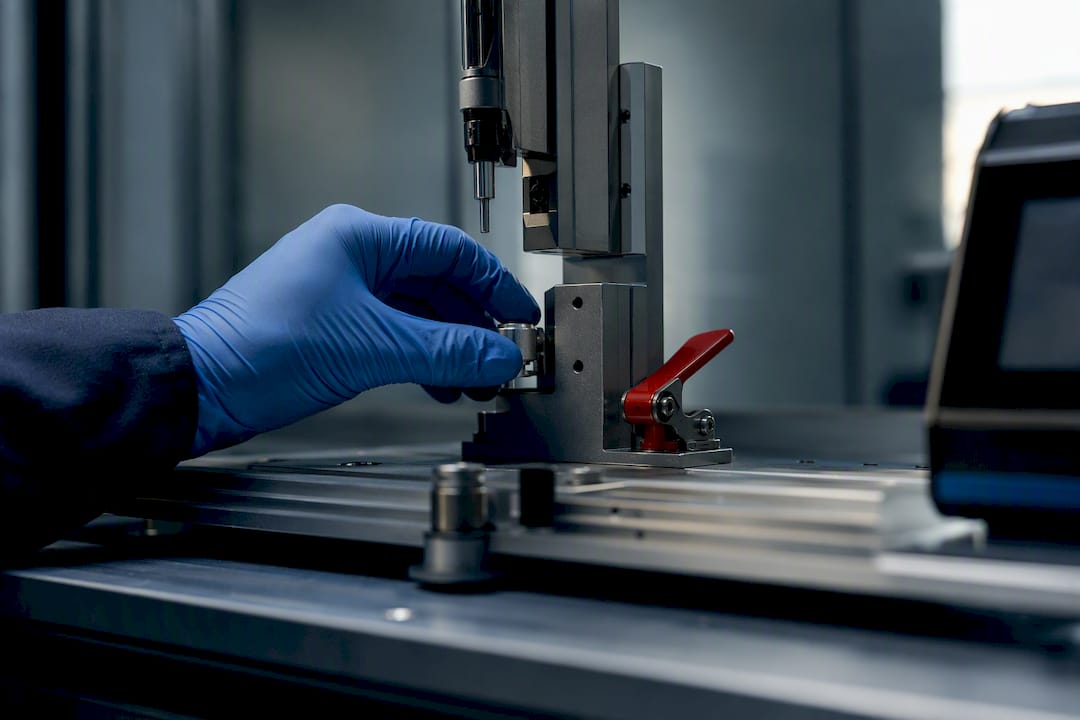
The utilisation breakeven rule backs this up directly: if an instrument is used less than about 60 to 70% of the time, roughly under 30 to 35 weeks a year, renting is typically more cost effective than ownership. Below that threshold, the fixed costs of ownership, calibration, storage, insurance, just don’t get spread across enough working days to pay for themselves.
Renting also carries operational perks that go beyond the sticker price:
A lab bridging a grant delay, or a manufacturer supporting a fixed term contract, gets the instrument it needs without the ownership tail that follows once the project ends.
Ownership earns its keep when an instrument runs continuously and sits at the centre of a process you can’t afford to interrupt. Permanently installed end of line test stations, daily use balances on a QC bench, or gauges tied to an audit trail all fall into this camp.
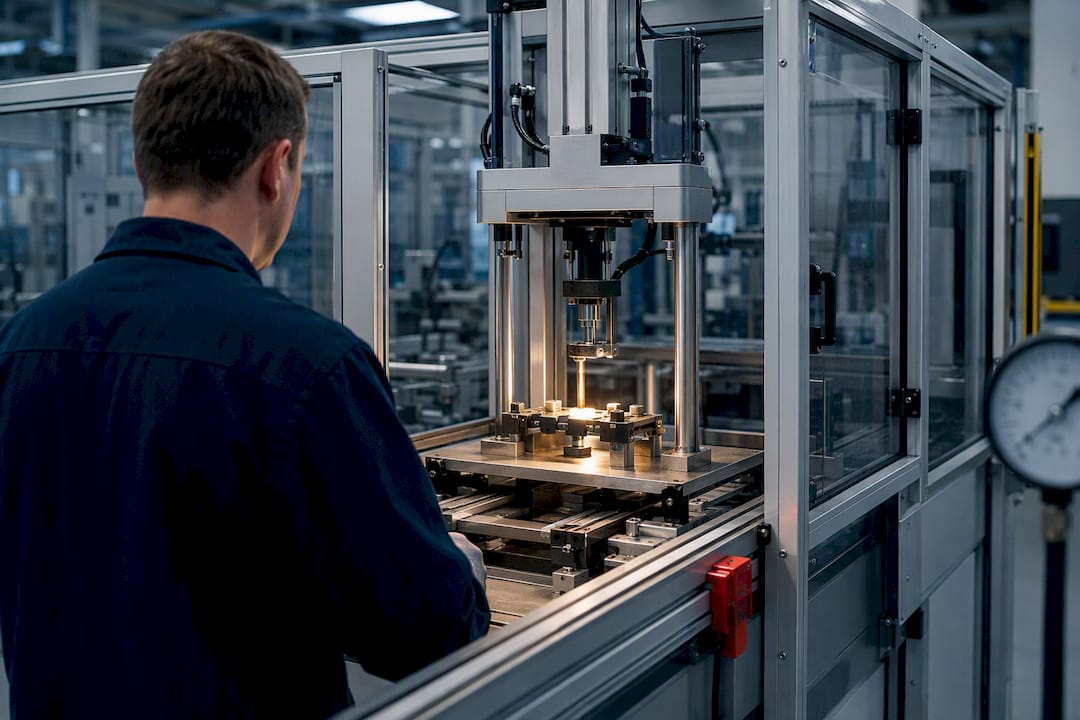
Continuous, permanently installed systems favour buying over renting, largely because ownership gives you long term cost control and the freedom to customise the setup to your process. Buying also builds a stable calibration history against a single serial number, which matters a great deal in audit heavy environments.
Reasons buying or leasing tends to win:
If cash flow is tight but ownership is still the goal, a lease or loan structure gets you there without draining the capital budget in one hit.
Five acquisition structures cover most scenarios in lab and industrial metrology, and each treats cash flow and accounting differently:
Before signing anything, check whether calibration and servicing are bundled into the contract, what the residual value assumption is, and what an early exit actually costs. Those three clauses decide whether the deal is genuinely flexible or just renting dressed up as a lease.
Purchase price is the smallest line item most procurement teams model, and that’s the problem. A realistic total cost of ownership calculation needs to cover:
Annual calibration commonly takes an instrument out of service for one to two months, and calibration costs typically range from several hundred to a few thousand euros depending on the instrument type, according to cost analysis from RentalTec.
Maintenance budgeting follows a similar rule of thumb: budget roughly 2 to 5% of the instrument’s value per year for repairs and upkeep, with depreciation running steeper again for high-end test gear. Fast-changing technology compounds the problem, because when specifications risk going stale within three to five years, renting quietly shifts the breakeven point in its own favour. Run these numbers against your actual usage pattern, not the vendor’s brochure figures, and the rent-versus-buy answer usually becomes obvious fast.
Work through these questions in order, and the right acquisition path usually falls out on its own:
Skipping step five is the most common mistake. Procurement picks the cheaper option on paper, then quality assurance finds out six months later that the rental agreement doesn’t cover the calibration certificate format the auditor wants.
Most metrology fleets run better as a mix than as an all-or-nothing decision. The Nextgenindu on high-precision measuring instruments backs this up: a hybrid approach that buys core daily drivers and rents specialised or intermittent-use units can cut total fleet costs by an estimated 25 to 40%.
A workable split looks like this:
Pro Tip: Run your rental pool and owned fleet through the same calibration scheduling system. Splitting them across two tracking methods is how recalibration dates get missed.
Most clients don’t have a rent or buy problem, they have a utilisation guessing problem. Get that number right and the rest of the decision follows. With decades supporting Australian labs and manufacturers, we’ve seen both paths work, provided calibration and compliance stay non-negotiable.
— Nima
This option keeps rent, lease and buy decisions genuinely open, supporting all three paths without steering you toward whichever path suits the provider better. Our Hire Equipment service covers short-term and seasonal needs, our NATA Calibration and Traceable Calibration keep owned instruments audit-ready, and our Preventative Maintenance and Repairs services cover whichever equipment you end up committing to. If you’re weighing up a purchase, the full equipment catalogue covers balances, scales, data loggers and load cells across multiple brands.
If you’re still working through the utilisation numbers, get in touch for a tailored cost comparison or a fleet audit, and we’ll help you land on the mix that actually matches how your instruments get used.
Once an instrument runs above roughly 60 to 70% of available working weeks, ownership usually becomes more cost effective than renting. Below that threshold, the fixed costs of ownership rarely get spread across enough active days to beat a rental agreement.
Rental agreements commonly bundle calibration and servicing into the rental package, which limits downtime for the hirer. Always confirm this in writing before signing, since not every rental contract includes it. PCS Precision’s Hire Equipment service covers calibration as part of the arrangement.
An operating (FMV) lease is treated as OPEX and typically ends with the option to return, renew, or buy at fair market value. A capital or finance lease behaves more like a loan and usually transfers ownership at the end for a nominal fee.
Rental and operating lease payments are generally treated as an operating expense, deductible as they’re incurred, while a purchased instrument is depreciated over its useful life. Which treatment suits your business depends on your cash position and tax structure, so it’s worth checking with your accountant before committing either way.
Yes, and it’s often the most cost-effective approach. A hybrid fleet that buys daily-use, audit-critical instruments and rents specialised or intermittent-use units can cut total fleet costs by an estimated 25 to 40% depending on the mix.
